


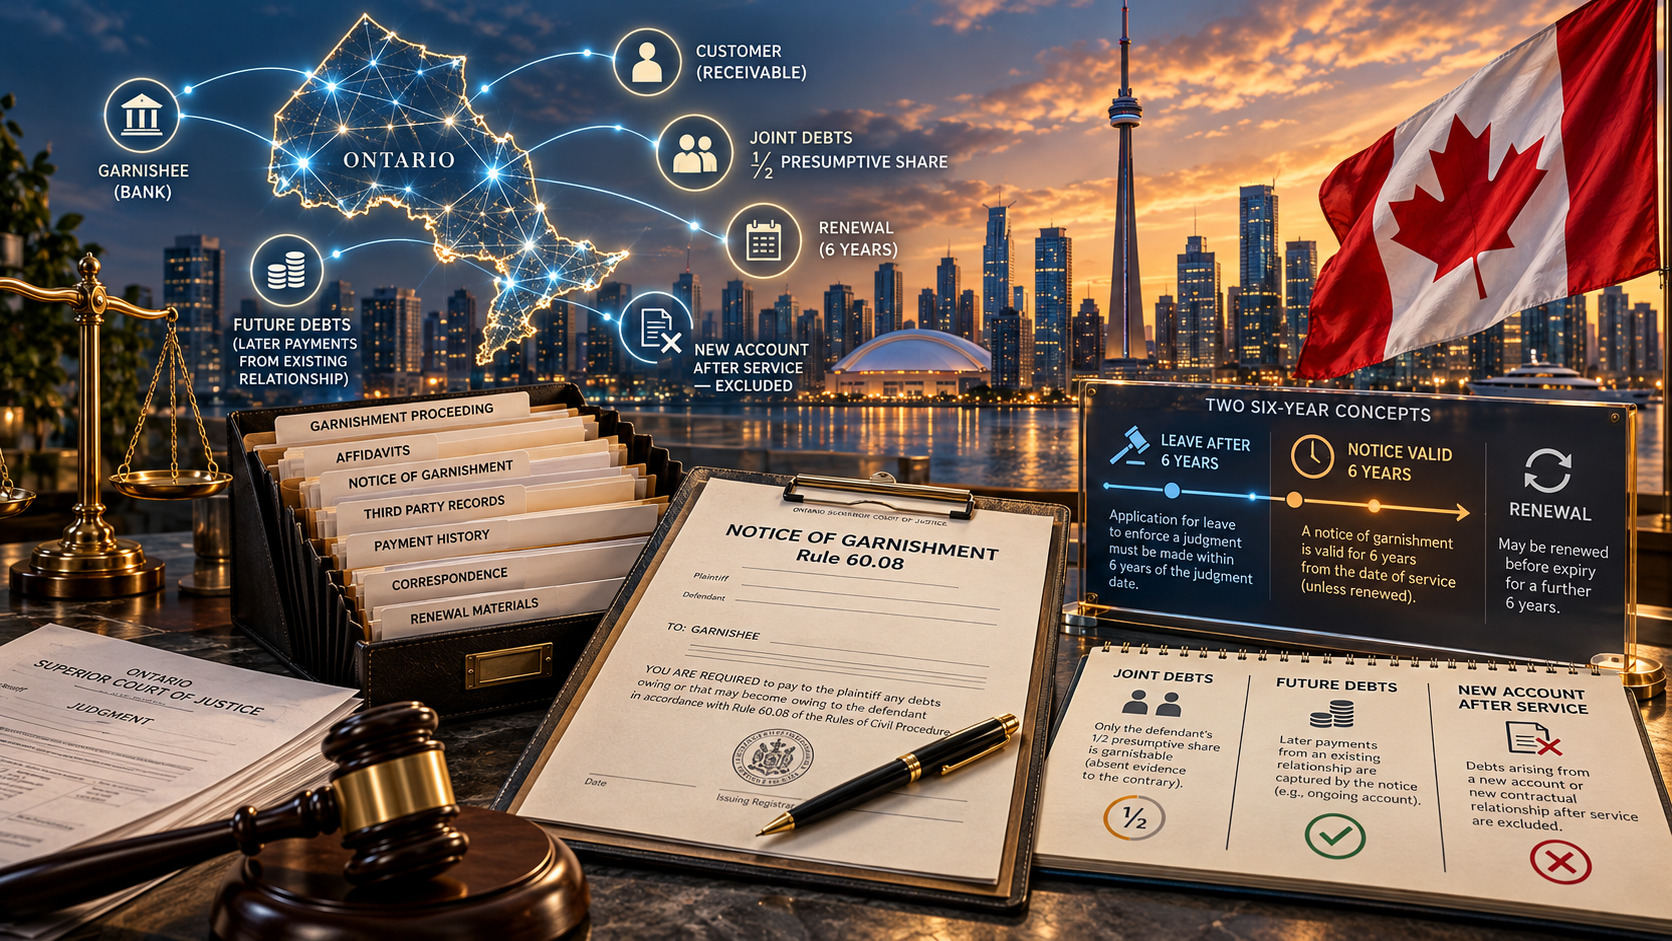
Ontario’s garnishment rule contains an unusual combination of time limits. A money order that is six years old may require court permission before a garnishment notice can be issued, while the notice itself can remain in force for six years and may be renewed for further six-year periods.
Those periods govern different things, and confusing them is only one of the traps in Rule 60.08 of Ontario’s Rules of Civil Procedure.
The same rule also limits what can be taken from a jointly owned debt, allows certain debts that become payable later to be caught by an existing notice, and yet excludes some relationships created only after the notice was served — including a bank account opened later with the same financial institution.
The result is a garnishment mechanism that can operate for years without functioning as a blanket attachment over everything the debtor may later receive. For a creditor enforcing a judgment in Ontario, the dates, ownership structure and legal origin of the garnished debt can matter just as much as its amount.
Rule 60.08 is an enforcement remedy, not a way to establish the debt
Rule 60.08 applies where a creditor has an order for the payment or recovery of money. It allows that order to be enforced against debts payable to the judgment debtor by a third party — the garnishee.
Depending on the circumstances, the garnishee may be a financial institution, an employer, a customer of a debtor company or another person that owes money to the judgment debtor.
This distinction is important because garnishment does not create an obligation that did not otherwise exist. The creditor must identify a debt capable of being garnished and then determine whether it falls within the temporal, ownership and procedural rules governing the notice.
Six years since the order is not six years since the notice
Rule 60.08 contains two different six-year concepts that should not be treated as interchangeable.
The first concerns the age of the underlying court order.
If six years or more have passed since the date of the order, a creditor generally cannot simply issue a notice of garnishment. Leave of the court is required first. Leave is also required where enforcement of the order is subject to a condition.
That means the creditor may face an additional procedural step before garnishment can begin at all.
There is another deadline attached to that permission. If the court grants leave but the notice of garnishment is not issued within one year, the leave ceases to have effect. The creditor may seek leave again, but cannot rely indefinitely on the earlier order granting permission.
The second six-year period concerns something entirely different: the life of the notice of garnishment after it has been issued.
This distinction can become important in older enforcement files. A relatively recent judgment may have a garnishment notice approaching expiry, while an older judgment may require court permission before a new notice can even be issued.
The two situations call for different action.
A garnishment notice can remain effective for six years — and be renewed
Once issued, a notice of garnishment remains in force for six years from its date of issuance.
Ontario’s rules also allow the notice to be renewed for a further six-year period. Further renewals are possible under the same framework.
The timing of renewal is important. Renewal must be addressed before the existing notice expires, so the expiry date should be treated as an enforcement deadline rather than an administrative detail.
For some creditors, this long duration can be commercially significant.
Consider a debtor company that is entitled to payments from a known customer over an extended period. If the relevant debts fall within the scope of the garnishment, a notice may continue to affect amounts becoming payable over time rather than operating only against money due when the notice was first served.
But a six-year notice does not amount to a six-year attachment of every asset the debtor may acquire.
The duration of the notice and the scope of the debts caught by it are separate questions.
A creditor therefore needs to monitor both: how long the notice remains in force and what legal obligations the notice actually reaches.
Joint debt does not automatically mean the whole amount can be taken
Rule 60.08 also contains a specific rule for a debt payable jointly to the judgment debtor and one or more co-owners.
The starting point is not that the creditor can garnish the entire amount.
Instead, one-half of the indebtedness is treated as garnishable unless the court determines that a greater or lesser amount should apply.
That distinction matters whenever the garnishee’s payment obligation is owed jointly to the judgment debtor and another person.
It would therefore be unsafe to assume that the face value of a joint debt represents the amount available to satisfy the judgment.
The rules also recognize the position of the co-owner. Where the garnishee identifies a debt as jointly owed, the co-owner must be brought into the process through the required notice procedure. If the respective rights of the parties are disputed, the court may determine the interests and liabilities of the judgment debtor, garnishee, co-owner and other affected persons at a garnishment hearing.
For the creditor, this makes the ownership analysis an important part of enforcement planning.
Before estimating how much a garnishment may recover, it may be necessary to establish:
- who is legally entitled to the debt;
- whether the debtor’s interest is sole or joint;
- whether another person claims an interest in the funds;
- and whether there is a basis for the court to depart from the one-half starting point.
A reference to joint ownership in banking or commercial records should therefore not be treated as a complete answer. The legal nature of the debt still needs to be examined.
The notice may reach debts that become payable later
One of the more powerful features of Ontario garnishment is that it is not necessarily limited to money already payable when the notice is served.
The rules can extend to a debt that becomes payable during the six-year period following service of the notice. They can also apply where payment becomes due upon fulfilment of a condition within that period.
This can be particularly important where the judgment debtor has an ongoing commercial relationship with a known third party.
For example, a customer may owe a debtor company money under an existing contractual arrangement even though the relevant payment date has not yet arrived. The fact that payment will occur later does not by itself place the obligation outside the garnishment.
The same issue can arise with conditional payments.
A sum may depend on completion of contractual work, delivery, certification, expiry of a payment period or satisfaction of another condition. If the underlying debt falls within Rule 60.08, the notice can have consequences beyond the amount immediately payable on the date of service.
Ontario appellate litigation has also shown that this continuing obligation is not merely theoretical. A garnishee must respond accurately to the garnishment process, and a materially inaccurate statement can have serious procedural consequences.
For the creditor, identifying the garnishee is therefore only the beginning.
The more important questions may be:
What obligation does the garnishee owe? When will it become payable? And does that obligation fall within the scope of the existing notice?
A future debt and a new relationship are not the same thing
The ability to reach later payments has an important limit.
Rule 60.08 distinguishes between a debt that becomes payable later and certain new relationships created only after the notice has been served.
That distinction is particularly important for bank accounts.
Where the garnishee is a financial institution, money in an account opened after service of the notice is excluded from the relevant future-debt rule.
The consequence can be counterintuitive.
A creditor may have served a valid notice on a bank. The notice may still have years left to run. The debtor may later open another account with the same institution.
Yet the continuing existence of the original notice does not automatically mean that money in the later-opened account is caught by it.
The account-opening date can therefore become a decisive fact.
Similar exclusions apply in other contexts.
If an employment relationship begins only after service of the notice, debts arising from that new employment relationship are not treated in the same way as amounts arising from employment already within the notice.
Likewise, a debt arising under an insurance policy entered into after service is excluded from the relevant future-debt concept.
This reveals one of the most important limits of long-term garnishment in Ontario:
a notice may follow certain debts into the future, but it does not automatically follow the debtor into every new economic relationship created afterwards.
What the creditor should establish before relying on garnishment
For a foreign creditor pursuing debt collection in Canada, an Ontario garnishment can be particularly effective when the debtor’s bank, customer or another source of payment has already been identified.
But identifying the garnishee is only the first step. The creditor still needs to determine whether the relevant debt falls within the scope of Rule 60.08, whether any time limits apply and whether the debtor’s interest is sole or joint.
Before relying on garnishment, the creditor should establish:
- whether there is an enforceable order for the payment or recovery of money;
- how much time has passed since the order was made;
- whether leave of the court is required before a notice can be issued;
- when an existing notice was issued and when it will expire;
- whether renewal needs to be completed before expiry;
- what legal debt the garnishee actually owes to the judgment debtor;
- whether that debt is owned solely or jointly;
- when the underlying obligation arose;
- whether a later payment comes from an existing relationship or a new one created after service;
- and whether any statutory limitation affects what can actually be recovered.
The chronology is often as important as the amount.
Knowing that the debtor banks with a particular institution may not be enough if the relevant account was opened after the notice was served. Knowing that a customer continues to do business with the debtor may not be enough without determining the legal basis on which future payments arise. And keeping a garnishment file open for several years does not eliminate the need to monitor the expiry and renewal of the notice.
Ontario Rule 60.08 is therefore more than a mechanism for intercepting money already in the hands of a third party.
It can operate over an extended period and reach certain debts that become payable later. At the same time, its effectiveness depends on several distinctions that are easy to overlook: the age of the judgment versus the age of the notice, the debtor’s share of a jointly owned debt, and the difference between a future payment and a new relationship created after service.
For a creditor planning enforcement in Ontario, those distinctions can determine whether garnishment becomes a durable recovery tool or reaches far less than expected.


