
A creditor has obtained a judgment in England and Wales, but the debtor still does not pay. There are indications that the debtor banks with a particular institution, yet the creditor does not know the account number, the branch or the current balance.
Can the creditor apply for a third party debt order and make the bank identify the account?
Potentially, yes. But there is an important dividing line.
A third party debt order cannot be used simply to test banks at random in the hope that one of them holds the debtor’s money. Before an interim order is made against a bank or building society, the creditor must provide evidence substantiating the belief that the debtor actually has an account with that institution.
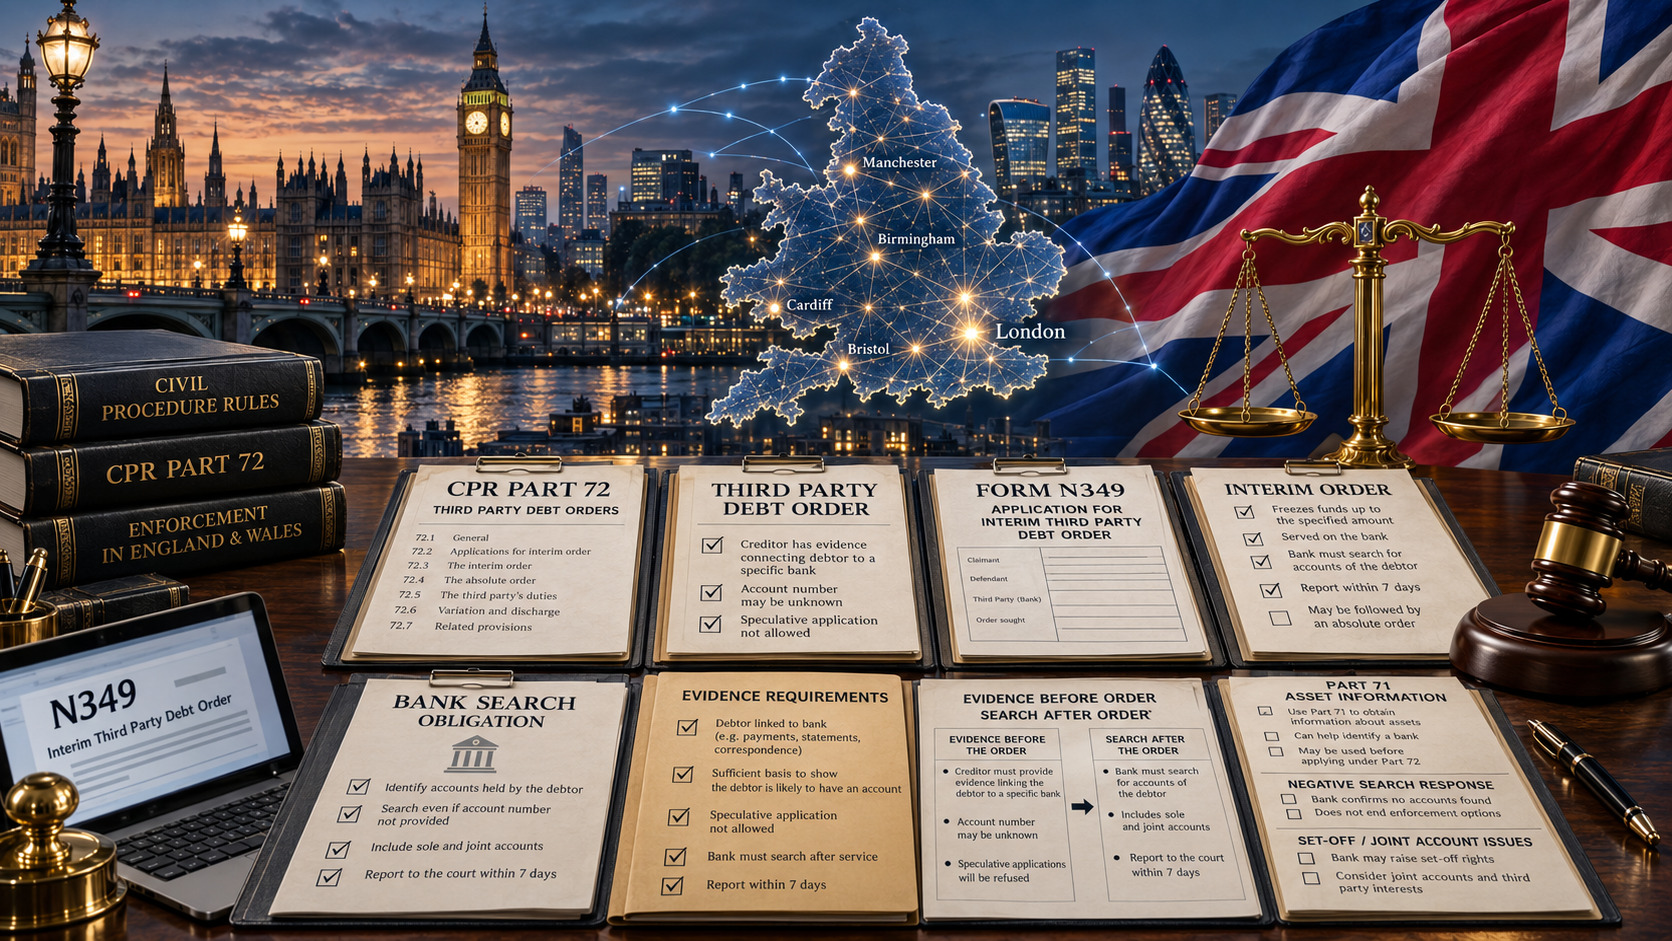
At the same time, the creditor does not necessarily have to know the account number or every banking detail in advance. If an interim third party debt order is made and served, CPR Part 72 then imposes a separate search and disclosure obligation on the bank.
For an overseas creditor, understanding this distinction can determine whether a third party debt order is a targeted enforcement measure or an unsuccessful attempt to use enforcement proceedings as an asset search.
A third party debt order is not a general bank-search mechanism
CPR Part 72 allows a judgment creditor to seek payment from a third party that owes money to the judgment debtor. In the banking context, the mechanism can be used against money standing to the credit of the debtor with a bank or building society.
The process begins with an application for an interim third party debt order. Practice Direction 72 requires the application to be made using Form N349 and to provide information about the judgment, the amount outstanding, the third party and the basis on which the creditor believes that the third party holds money for the debtor.
The critical restriction appears in paragraph 1.3 of Practice Direction 72.
The court will not grant a speculative application for a third party debt order. Where the proposed third party is a bank or building society, the application must contain evidence substantiating the creditor’s belief that the judgment debtor has an account with that particular institution.
This means that a creditor should not treat Part 72 as a method of sending applications to a list of major banks merely to discover whether the debtor happens to bank with one of them.
There must already be an evidential basis connecting the debtor with the particular bank.
The strength of that evidence will depend on the facts. The rules do not prescribe one universal document that must always be produced. The important point is that the belief must be capable of being explained and supported rather than being based on guesswork.
The creditor may not need to know the account number
The prohibition on speculative applications does not mean that the creditor must already possess complete banking details.
Practice Direction 72 expressly contemplates incomplete information.
Where the third party is a bank or building society, the N349 application normally identifies the bank, the branch where the account is believed to be held and the account number. However, paragraph 1.2(6) provides that where the judgment creditor does not know all or part of that information, the application can state that fact.
This distinction is important.
A creditor may therefore be able to make a properly supported application even though the exact account number is unknown. What the creditor cannot dispense with is the evidential connection between the debtor and the particular bank.
For example, there is a significant difference between these two situations:
- the creditor possesses previous payment instructions showing that the debtor used a particular bank but no longer knows whether the same account number remains current;
- the creditor has no debtor-specific banking information and simply believes that the debtor is likely to use one of several large UK banks.
The first situation may provide evidence capable of supporting a targeted application, depending on the age, reliability and context of the information.
The second is much closer to the speculative exercise that Practice Direction 72 is intended to prevent.
What must the creditor explain to the court?
Practice Direction 72 requires more than naming a bank.
The creditor must confirm, to the best of its knowledge or belief, that the third party is within the jurisdiction and owes money to, or holds money to the credit of, the judgment debtor. The application must also identify the sources or grounds of the relevant knowledge or belief.
In practical terms, a creditor preparing a bank-based third party debt order should be able to answer two different questions:
Why do we believe this debtor banks with this institution?
What evidence supports that belief?
Depending on the case, potentially relevant evidence may come from:
- bank details previously provided by the debtor for payments;
- earlier transfers to or from the debtor;
- invoices, contracts or payment instructions identifying banking arrangements;
- correspondence in which the debtor provided or confirmed account details;
- bank statements or financial documents obtained lawfully during litigation or enforcement;
- information disclosed by the debtor or an appropriate company officer;
- reliable information obtained through lawful asset-tracing work; or
- other documents creating a sufficiently specific connection between the debtor and the bank.
These are practical examples rather than an exhaustive statutory list.
A historic account reference may require further investigation. A document relating to a company within the same corporate group does not automatically establish that the judgment debtor itself holds an account. Information about a beneficial interest in another customer of the bank is also not necessarily equivalent to an account held by the judgment debtor.
The purpose of the evidence is not merely to demonstrate that an application form has been completed. It is to show why the court should use an enforcement power against the particular third party identified.
CPR Part 71 may provide the missing banking information
This is where different enforcement mechanisms can work together.
If the creditor has a judgment but does not yet know where the debtor’s assets are located, immediately filing third party debt order applications may be premature.
For a corporate judgment debtor, information obtained under CPR Part 71: compelling a company officer to disclose assets may help identify bank accounts, bank statements, receivables and other information relevant to enforcement.
Part 71 serves a different purpose from Part 72.
It is principally an information-gathering mechanism. The creditor may seek an order requiring an appropriate officer of a corporate judgment debtor to attend court, produce specified documents and answer enforcement-related questions on oath.
If that process identifies a particular bank used by the company, the information may materially change the enforcement position.
The creditor is no longer simply guessing where money might be held. It may now have evidence supporting an application directed at a specific bank.
The sequence can therefore be:
Identify the asset or institution → establish an evidential basis → choose the appropriate enforcement measure.
For an international creditor unfamiliar with the debtor’s banking arrangements in England and Wales, this sequence can be more effective than attempting enforcement measures before the asset picture is sufficiently clear.
After service, the bank has its own search obligation
The legal position changes once the court has made an interim third party debt order and the order has been served on the bank.
Under CPR 72.6, a bank or building society served with an interim third party debt order must carry out a search to identify accounts held with it by the judgment debtor.
This is the key distinction at the centre of the procedure.
Before the interim order, the creditor must provide a proper evidential basis for targeting the particular bank. After service of the interim order, the rules impose a search obligation on the bank itself.
The interim order also becomes binding on the third party when it is served. The order specifies the amount that the third party must retain pending further consideration of the application.
The bank is therefore not merely being asked informally whether it recognises the debtor’s name. It is responding to a court order within a defined enforcement procedure.
What information must the bank provide?
CPR 72.6 sets a short timetable.
Within seven days after service of the interim order, the bank or building society must disclose prescribed information to the court and the judgment creditor in respect of the relevant accounts.
Where an account is identified, the required information includes:
- the account number;
- whether the account is in credit;
- whether the credit balance is sufficient to cover the amount specified in the order;
- where the balance is insufficient, the amount standing to the credit of the account when the order was served; and
- whether the bank asserts a right to the money, including a right of set-off, together with the grounds for that assertion.
A negative search result does not simply end the bank’s obligations silently.
If the judgment debtor does not hold an account with the institution, the bank must inform the court and the judgment creditor of that fact within seven days.
The same reporting obligation applies where the bank cannot comply for another reason, for example because the information in the order matches more than one account holder and the bank cannot identify which person is the judgment debtor.
This makes the response useful even where no attachable balance is ultimately found.
The creditor may learn that the information relied upon is outdated, that the account cannot be identified from the details supplied or that the debtor no longer maintains an account with that institution.
Al Haroun v Al Sabah shows why a negative result still matters
The operation of the bank’s duty was considered in Al Haroun v Al Sabah [2026] EWHC 1669 (KB).
The underlying judgment creditor had obtained an interim third party debt order against Kuwait Finance House plc, formerly Ahli United Bank (UK) plc.
The bank accepted that the interim order had been properly served and had reached senior management.
According to the evidence recorded by the High Court, bank personnel carried out searches designed to identify accounts held personally by the judgment debtor. The searches included records relating to existing and former customers over the preceding eight years and checks of anti-money-laundering systems.
No personal account was identified by those searches.
The problem was what happened next.
The bank did not inform the court or the judgment creditor of the negative result. A senior bank witness explained that he had understood the order to mean that no response was required if the bank held no account in the judgment debtor’s name.
The court stated that this understanding was wrong.
CPR 72.6 required the bank to report the negative result within seven days.
The case is useful because it illustrates an aspect of Part 72 that may otherwise be overlooked: the bank’s obligation is not limited to freezing money when an account is found. The rules also require a response when no account is identified.
The decision should not, however, be read too broadly.
The judgment did not establish that every bank must use the exact same internal search methodology used in that particular case. Nor did the court determine at that hearing whether the judgment debtor actually had an account with the bank; that issue was outside the scope of the matters the judge was deciding.
The practical lesson is narrower but important: once an interim third party debt order has been served, a bank cannot simply remain silent because its search produces no account.
The bank-search obligation has limits
The search obligation under CPR Part 72 is not unlimited.
Practice Direction 72 provides that, unless the interim order states otherwise, a bank or building society is required to retain money in and disclose information about accounts held solely by the judgment debtor.
Where there are joint judgment debtors, the rules also address accounts held jointly by them or solely by one or more of them.
By contrast, the ordinary rule does not require the bank to retain money in or disclose information about an account held jointly by the judgment debtor and another person who is not also a judgment debtor.
That limitation can be significant.
A creditor who has evidence that the debtor uses a joint account should not assume that an ordinary bank-based third party debt order will operate in exactly the same way as it would against an account held solely by the debtor.
Joint accounts therefore require separate analysis rather than being treated as merely another account identified during the bank’s search.
A successful search does not automatically mean that the creditor receives the money
The obligation to search should also be distinguished from the final recovery of funds.
A third party debt order is a court enforcement procedure with an interim and a final stage. The fact that a bank identifies an account does not by itself establish that the creditor is automatically entitled to every sum associated with that account.
Among other matters, the rules specifically require disclosure of any right asserted by the bank over the money, including a right of set-off.
There may also be disputes concerning ownership of the money or claims by another person. CPR Part 72 contains procedures allowing relevant objections and competing claims to be considered before a final order is made.
For that reason, the useful question before applying is not simply:
Does the debtor have a bank account?
The creditor should also consider:
Is there a realistic prospect that the account contains money that can actually be reached through this enforcement procedure?
A technically successful application that identifies an empty account, a balance already absorbed by a valid bank claim or another material obstacle may produce information without producing meaningful recovery.
What an overseas creditor should establish before filing N349
Before applying for a bank-based third party debt order in England and Wales, an overseas creditor should prepare a short enforcement file addressing the information that the court and the procedure actually require.
The review should normally include:
- The enforceable judgment or order. Confirm what remains unpaid and whether enforcement can presently proceed.
- The identity of the proposed bank. Identify the particular institution against which the application is contemplated.
- The evidential connection. Record precisely why the creditor believes the judgment debtor has an account with that institution.
- The source of that information. Preserve the document, disclosure, payment record, statement, correspondence or other evidence supporting the belief.
- Known and unknown account details. Separate what is actually known from what remains unknown rather than filling gaps with assumptions.
- The age of the information. Banking arrangements can change. Evidence that was reliable several years ago may justify further investigation before an application is filed.
- The identity of the account holder. Check whether the evidence relates to the judgment debtor itself, another group company, a director, a beneficially owned company or a different person.
- Possible joint ownership. If there are indications of a joint account, consider the limits imposed by Practice Direction 72 before assuming that the ordinary search and retention rules will apply.
- Alternative information procedures. Where the evidence is still too weak, consider whether Part 71 or other lawful asset-tracing work should be used before choosing a bank-based enforcement measure.
- The expected commercial outcome. Assess whether there is reason to believe that meaningful funds may be available and whether the likely recovery justifies the enforcement step.
The broader choice between third party debt orders and other enforcement measures should be made in the context of the debtor’s actual assets. Grandliga’s guide to debt collection in the United Kingdom provides the wider framework for court proceedings and enforcement across the different UK legal systems.
Part 72 itself should be treated specifically as an England and Wales procedure, not as a uniform enforcement mechanism for Scotland and Northern Ireland.
The practical distinction is evidence before the order, search after the order
A third party debt order creates an unusual but important division of responsibility.
The creditor does not have to arrive with every banking detail already known. Practice Direction 72 expressly allows the application to state that some information, including the account number, is unknown.
But that flexibility does not turn Part 72 into a discovery exercise.
Before the interim order is made, the creditor must provide evidence substantiating the belief that the judgment debtor has an account with the particular bank being targeted. A list of possible banks and a hope that one of them will find something is not the same thing.
Once the interim order has been made and served, the position changes. The bank then has its own duties under CPR 72.6 to conduct the required search and provide the prescribed information within seven days, including a negative response where no relevant account is identified.
For an international creditor, the practical strategy is therefore straightforward: investigate first, identify the bank on evidence, and use Part 72 as a targeted enforcement tool rather than as a substitute for asset tracing.
Where the debtor’s banking arrangements are unknown, an information procedure such as CPR Part 71 may help establish the missing link. Where reliable evidence already points to a particular bank, the absence of the exact account number does not necessarily prevent a properly supported application.
That distinction can determine whether a third party debt order becomes an effective route from judgment to recoverable funds or an application that fails before the bank is ever required to search.


