
A lender may have a valid security agreement, a registered security interest and a clear event of default, yet still be unable to move immediately against a Canadian debtor’s business assets. Where section 244 of the federal Bankruptcy and Insolvency Act applies, a secured creditor must first send a prescribed notice of its intention to enforce the security and, subject to limited exceptions, wait ten days before enforcement begins.
For an overseas bank, fund, trade financier or other secured creditor, this is more than a technical notice requirement. It can affect the timing of a receivership, the sequencing of enforcement steps and the practical strategy for protecting collateral while a debtor is deteriorating financially.
When section 244 notice is required
Section 244(1) applies where a secured creditor intends to enforce security over all or substantially all of the insolvent person’s inventory, accounts receivable or other property that was acquired for, or is used in relation to, the debtor’s business.
The rule therefore does not apply merely because a creditor happens to hold security. Its application depends on several elements that should be checked before enforcement:
- the creditor must be a secured creditor;
- the debtor must be an “insolvent person” for purposes of the Act;
- the creditor must intend to enforce its security;
- the security must extend to all or substantially all of the relevant category of business property.
This distinction matters in cross-border transactions. A foreign creditor may focus first on the wording of the loan agreement or security document, while the federal insolvency regime may impose an additional procedural requirement once the debtor is insolvent and the enforcement is sufficiently broad.
The notice must use the prescribed form
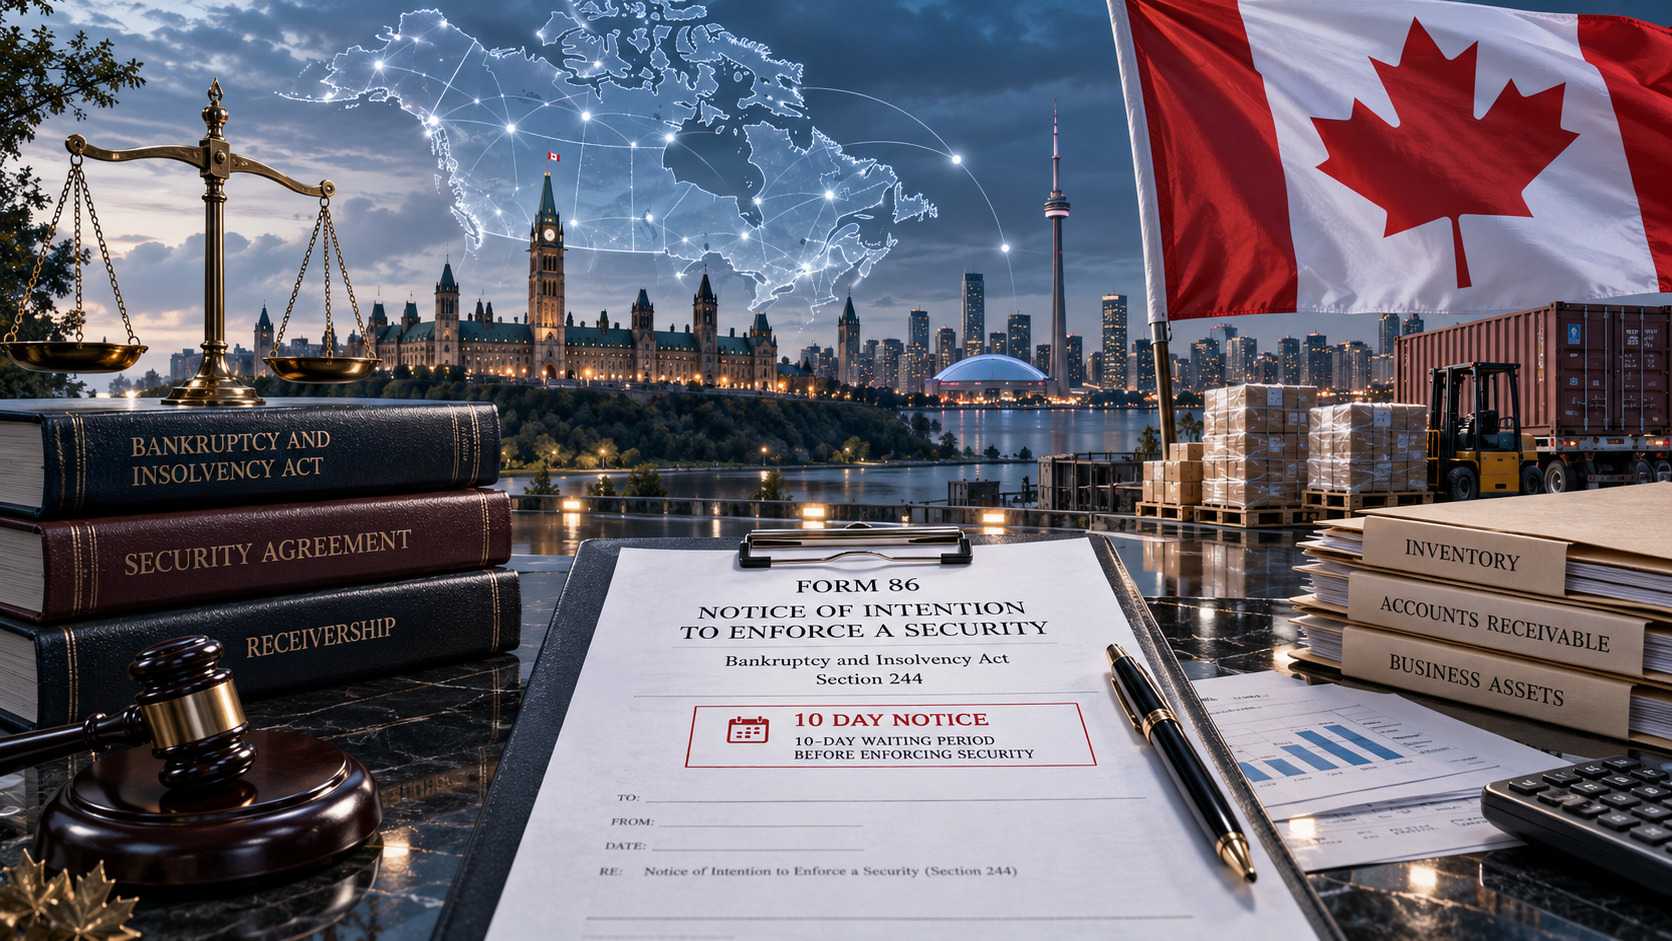
The notice is not simply a demand letter created by the creditor. The Office of the Superintendent of Bankruptcy publishes Form 86 — Notice of Intention to Enforce a Security, prescribed under Rule 124. The form identifies the secured creditor, describes the property and security to be enforced, states the amount of secured indebtedness and records that enforcement cannot occur until the ten-day period has expired unless the debtor consents to earlier enforcement.
This makes the preparation of the notice an evidentiary as well as procedural exercise. Before sending it, the creditor should be able to identify accurately:
- the security documents being relied upon;
- the collateral covered by those documents;
- the amount of secured indebtedness;
- the debtor to whom the notice must be sent;
- the method of service required by the applicable rules and contractual arrangements.
A defect in this preparation can create avoidable disputes at precisely the stage when speed is most important.
What the ten-day period actually prevents
Section 244(2) provides that, where the notice is required, the creditor must not enforce the relevant security until ten days have expired after the notice is sent.
The important point is that this is not a general ten-day debt collection period. It does not mean that every Canadian creditor must wait ten days after default, nor does it create a universal grace period for every secured loan.
It is a specific statutory restriction connected to enforcement of security falling within section 244.
For a foreign creditor, the practical consequence is straightforward: the projected enforcement timetable should not begin with seizure, realization or appointment steps as though the contractual default clause were the only relevant trigger. The section 244 analysis should occur before the first enforcement action is taken.
A pre-signed waiver cannot eliminate the waiting period
The Act allows the insolvent person to consent to earlier enforcement. However, section 244(2.1) contains an important protection: the secured creditor cannot obtain that consent before the section 244 notice has been sent.
That restriction prevents the ten-day period from being routinely neutralized in advance through boilerplate wording in a credit or security agreement.
For example, a clause signed when financing is first advanced cannot simply provide that the borrower permanently waives the future section 244 waiting period and thereby give the lender an automatic right to immediate enforcement years later. If earlier enforcement is contemplated, the relevant consent must be obtained after the statutory notice has been sent.
For lenders using international facility documentation, this is a point worth checking carefully. Contractual enforcement language that may be effective in another jurisdiction should not be assumed to displace Canadian insolvency legislation.
The rule also affects a court-appointed receiver
The ten-day period can become particularly important where the secured creditor intends to seek a receiver under section 243 of the Bankruptcy and Insolvency Act.
Section 243(1) permits a court, on the application of a secured creditor, to appoint a receiver where the court considers it just or convenient. The receiver may take possession of all or substantially all relevant business property, exercise control over that property and the debtor’s business, and take other action authorized by the court.
But section 243(1.1) expressly links the receivership process to section 244. Where a section 244 notice is required, the court generally may not appoint the receiver before ten days have expired after the notice was sent. There are two statutory routes to an earlier appointment: the debtor may consent to earlier enforcement, or the court may consider an earlier appointment appropriate.
This is a critical planning point. A creditor preparing an urgent receivership application should not assume that service of court materials alone resolves the timing issue. The section 244 notice should be considered as part of the receivership strategy from the outset.
Urgent protection may still be possible
The existence of the ten-day period does not mean that assets must simply be left unprotected while the creditor waits.
Section 47 of the Act allows a court, in appropriate circumstances, to appoint an interim receiver where a section 244 notice is about to be sent or has already been sent. The court may authorize protective steps, including taking possession of property, exercising control over it, taking conservatory measures and, where necessary, disposing summarily of property that is perishable or likely to depreciate rapidly. The appointment must be shown to be necessary for protecting the debtor’s estate or the interests of the creditor who sent the notice.
Accordingly, an urgent risk of asset dissipation, deterioration or disappearance should not automatically lead a creditor to ignore the statutory notice regime. The better approach may be to preserve the assets through an appropriate court application while respecting the structure of the Act.
Section 244 is not the only enforcement rule
A section 244 notice should not be treated as a complete enforcement checklist.
Canada has both federal insolvency law and provincial or territorial rules governing security interests and realization. A creditor may also need to consider the governing personal property security legislation, the terms of the security agreement, priority arrangements, demands for payment, other statutory notices and any existing insolvency stay.
Section 244 itself contains exceptions. Among other things, the provision does not apply, or ceases to apply, in the circumstances described in section 244(3), and section 244(4) provides that it does not apply where there is already a receiver in respect of the insolvent person.
The practical lesson is that Form 86 is one component of the enforcement analysis, not a substitute for reviewing the complete security and insolvency position.
A practical example
Assume a foreign lender financed a Canadian operating company and holds a general security agreement covering substantially all of the company’s inventory, receivables and other business assets.
The borrower stops making payments and appears insolvent. The loan documents permit acceleration and enforcement following default.
The lender may be contractually entitled to demand repayment, but before enforcing its broad security it should determine whether section 244 applies. If it does, the creditor should prepare and send Form 86 and calculate the ten-day period before proceeding with enforcement.
If the lender intends to seek a national receiver under section 243, the same notice period becomes relevant to the timing of the receivership application. If there is a genuine danger that inventory will disappear or assets will rapidly lose value during that period, counsel can consider whether interim protective relief is appropriate rather than simply commencing enforcement prematurely.
What a foreign secured creditor should check before acting
Before enforcing security against a Canadian business, a foreign creditor should usually establish the following points:
- whether the debtor meets the relevant insolvency threshold;
- exactly which assets are covered by the creditor’s security;
- whether those assets amount to all or substantially all of the relevant business property;
- whether the security has been properly created, perfected and registered under the applicable provincial or territorial regime;
- whether section 244 requires Form 86;
- when and how the notice must be sent;
- when the ten-day period expires;
- whether the debtor has given valid consent to earlier enforcement after receiving the notice;
- whether a receivership, interim receivership or another enforcement route is being considered;
- whether any insolvency stay, priority claim or competing security affects the proposed action.
These checks should form part of the wider strategy for debt collection in Canada, particularly where the creditor is located abroad and enforcement involves secured business assets rather than an ordinary unsecured claim.
Why the ten days matter
Section 244 creates a short period, but an important one.
A creditor with strong contractual rights and properly documented security can still lose time, increase costs or face procedural objections if enforcement is launched without checking whether the federal notice requirement applies. Conversely, identifying the issue early allows the creditor to serve the notice while the rest of the enforcement strategy is being prepared.
For an overseas secured creditor, the priority is therefore not merely to ask whether the security is enforceable. The more useful questions are when enforcement may lawfully begin, whether Form 86 is required, what must happen during the ten-day period and whether protective court relief is needed before that period expires.


